The 62-to-64 Age Gap: Early Claimants Face Full Taxation
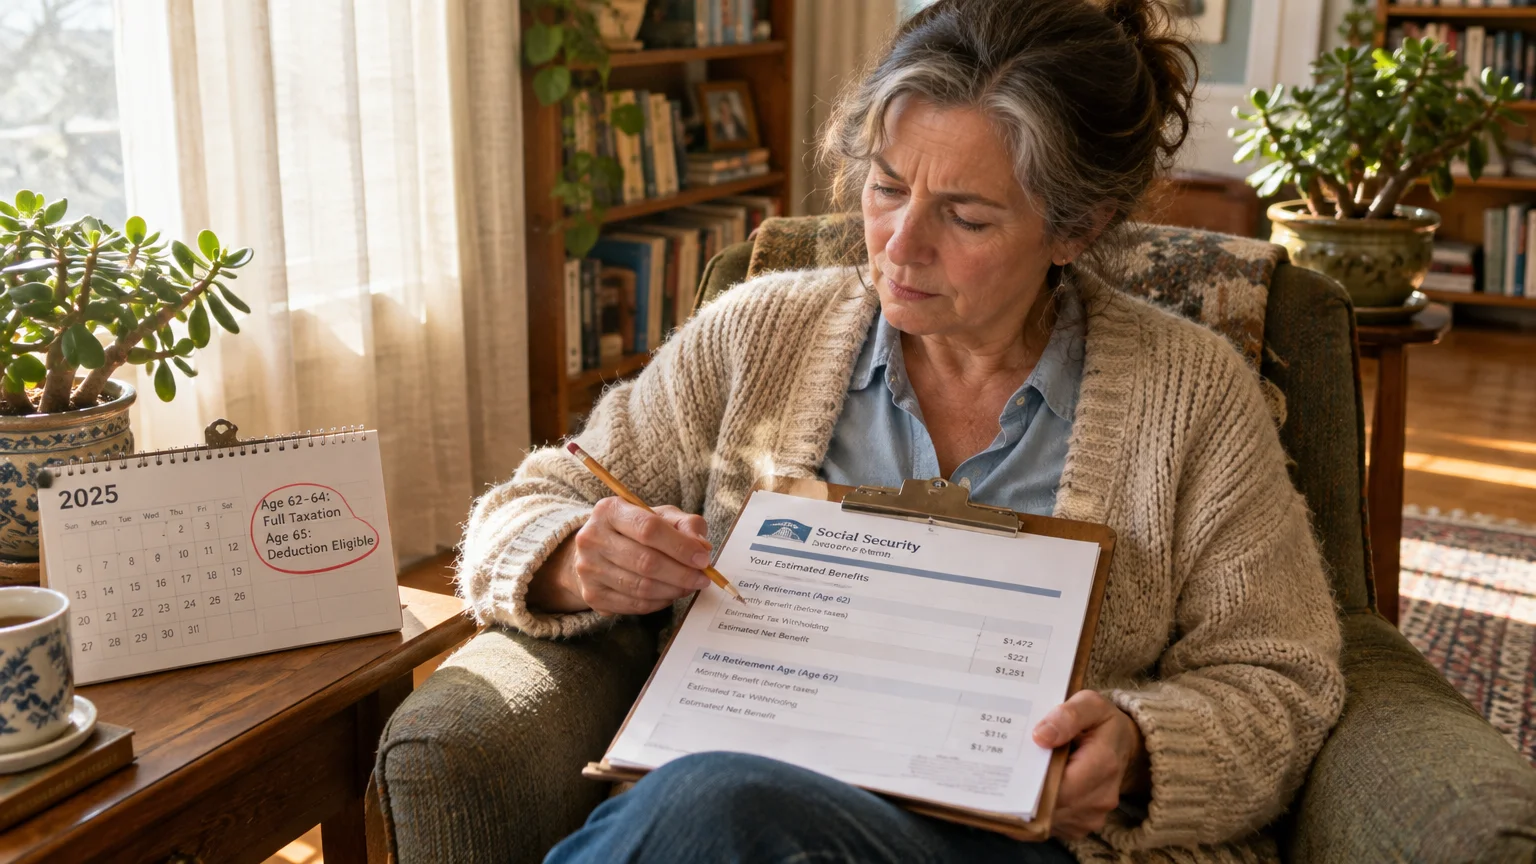
One critical nuance of the 2025 tax reform catches many early retirees off guard. The enhanced senior deduction applies strictly to individuals who have reached age 65.
If you claim Social Security at age 62, 63, or 64, you receive no Senior Bonus. You must wait until the tax year in which you turn 65 to claim the $6,000 deduction.
However, your Social Security benefits remain subject to the combined income formula immediately upon claiming. The $25,000 single and $32,000 married thresholds apply regardless of your age.
If you collect early benefits while working part-time or taking withdrawals, you could face unexpected taxes. You lack the extra $6,000 deduction to shelter that income.
Furthermore, early claimants who work remain subject to the Social Security retirement earnings test. Earning over the annual earnings limit triggers benefit withholding on top of regular taxes.
This gap penalizes early claimers who falsely believe all Social Security income is tax-free. If you are under 65, evaluate your tax exposure before initiating your benefits.
State-Level Social Security Taxes in 2026
While federal rules generate headlines, state income taxes also impact your bottom line. Fortunately, state-level taxes on Social Security have declined steadily across the country.
In a major victory for seniors, West Virginia completed the phaseout of its benefit tax. Beginning in the 2026 tax year, West Virginia fully exempts Social Security benefits from state income taxation.
West Virginia follows Kansas, Missouri, and Nebraska, which successfully repealed their state benefit taxes in 2024. Today, 42 states and Washington, D.C., levy zero state taxes on Social Security benefits.
In 2026, only eight states continue to tax Social Security benefits in any form. Those states are Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont.
Even within these eight states, generous income and age exemptions protect most middle-class retirees. For example, several states only tax benefits for residents earning above specific income thresholds.
If you live in one of these eight states, check your state revenue agency’s current deduction limits. Understanding your local rules prevents you from overpaying state taxes on your monthly benefits.