Retiring well on $65,000 a year feels nearly impossible when national home prices top $388,000 and 30-year mortgage rates hover above 7%. Moving to the right small town changes that math overnight.
Across the country, communities with lower housing costs, solid regional hospitals, and generous state tax exemptions let couples live comfortably without draining their savings. You can stretch Social Security and modest nest eggs much further when everyday bills stay predictable.
These 11 affordable small towns show how cheap places to retire for couples still deliver recreation, neighborly charm, and reliable care on a $65,000 annual budget.
What a $65,000 Retirement Budget Actually Buys in 2026
A $65,000 annual budget sits right in line with real-world retiree spending. According to U.S. Bureau of Labor Statistics data, households headed by someone ages 65 to 74 spent an average of $65,354 in 2024 and roughly $69,336 in 2025.
Spending tends to drop as you move into your mid-70s and beyond. Households age 75 and older averaged $55,834 in 2024 and about $57,960 in 2025, though healthcare rises from 11.8% to 14.2% of total spending.
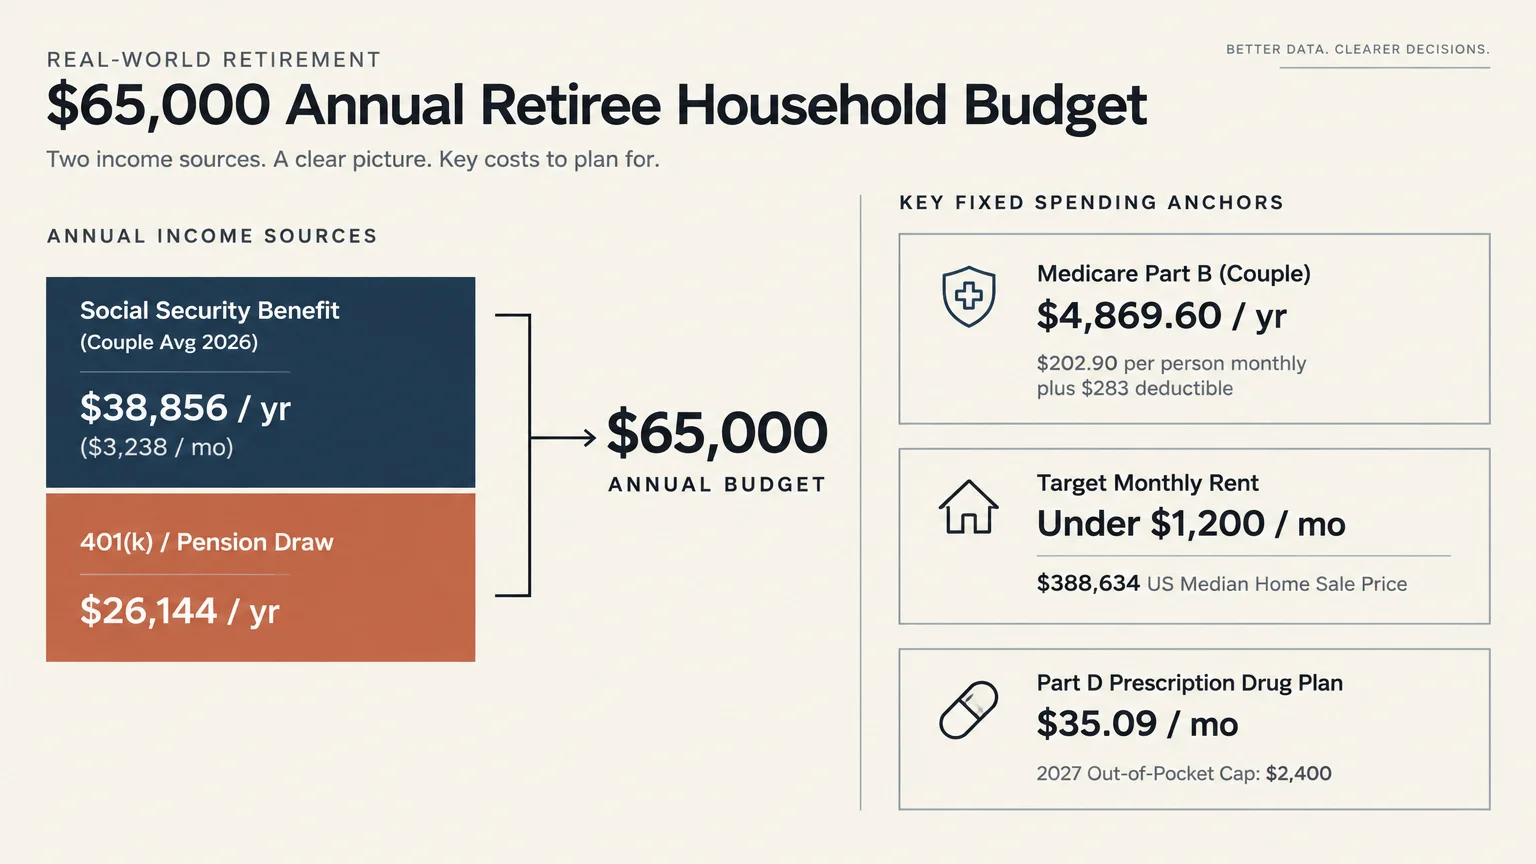
For many couples, Social Security covers more than half of a $65,000 lifestyle right out of the gate. An aged couple both receiving benefits averages $3,238 per month ($38,856 a year) in 2026, according to the Social Security Administration.
A 3.6% cost-of-living adjustment raises that couple’s average benefit to $3,355 per month ($40,260 a year) starting in January 2027. Drawing about $25,000 annually from a 401(k), pension, or part-time work bridges the remaining gap.
Fidelity Investments reports average 401(k) balances of $258,800 for ages 65 to 69 and $264,500 for ages 70 and older. Combined with home equity, that cushion makes small town retirement realistic for ordinary savers.
Before locking in a destination, carve out fixed space in your $65,000 plan for healthcare premiums. Standard Medicare Part B costs $202.90 per person monthly in 2026—or $4,869.60 a year for a couple—plus a $283 annual deductible per person.
Prescription coverage also shifts between 2026 and 2027 under Medicare.gov rules. Stand-alone Part D drug plans average $35.09 monthly in 2026 and are projected at $36 in 2027, while the annual Part D out-of-pocket cap rises from $2,100 to $2,400.
Housing remains the single biggest lever in your retirement cost of living. Redfin’s October 2026 median U.S. home sale price hit $388,634, while Zillow Home Loans put 30-year fixed mortgage rates between 7.13% and 7.49% in mid-November 2026.
Buying in an affordable town with existing home equity—or renting under $1,200 a month—shields you from high borrowing costs. Over 338,000 Americans moved in retirement over the past year, according to Hire A Helper data cited by NEA Member Benefits.
Side-by-Side Comparison of the 11 Affordable Small Towns
Every town below supports a $65,000 annual budget, yet each balances home prices, local taxes, and climate differently. Use this table to compare key numbers before exploring individual neighborhoods.
| Small Town | Typical Home Price | Typical Monthly Rent | State Tax Advantage | Watch-Out Factor |
|---|---|---|---|---|
| Midland, Michigan | Moderately below national norms | Moderate regional rents | Exempts Social Security; expanded 2026 retirement cap | Winter heating and snow removal |
| Decatur, Illinois | ~$89,855 median value | Low regional rents | Exempts all qualifying retirement income | Colder winters; smaller-city amenities |
| Fort Smith, Arkansas | $178,100–$195,029 | $884–$989 | Exempts Social Security | Hot, humid summers |
| Greeneville, Tennessee | $244,471 average | $1,050 | No personal income tax | Smaller local job and transit base |
| Macon, Georgia | $171,522 average | $1,150 | Exempts Social Security plus $65,000 per person (65+) | Summer heat and neighborhood variation |
| Sebring Area, Florida | ~$175,000 median value | Under $1,000 | No personal income tax | High Florida homeowners insurance |
| Green Valley, Arizona | $282,000 median single-family | Moderate 55+ rentals | Exempts Social Security | HOA fees and summer desert heat |
| Pahrump, Nevada | Affordable desert homes | Low-to-moderate rents | No personal income tax | Driving distance to Las Vegas specialists |
| Anaconda, Montana | $302,593 average | $1,350 | None | Montana taxes some Social Security benefits |
| Altoona, Pennsylvania | Budget-friendly local market | Budget regional rents | Exempts Social Security, pensions, and 401(k)/IRA withdrawals | Hilly terrain and winter weather |
| Saranac Lake, New York | $337,496 average | $2,500 | Exempts Social Security plus $20,000 per person (59½+) | High rent and steep heating bills |
Midwest and Great Lakes Towns With Deep Tax Breaks
Midwestern towns often pair low home prices with generous state exemptions on retirement income. You keep more of every pension or IRA dollar you withdraw while enjoying four distinct seasons.
1. Midland, Michigan
U.S. News & World Report ranked Midland #1 out of 859 cities in its 2026 Best Places to Retire. With roughly 42,500 residents per ReloMaps 2026 data, it delivers small-city calm without feeling isolated.
Active couples can spend their mornings along paved rail trails and wooded parks without paying resort prices. Strong local healthcare access makes Midland practical as you age in place.
Michigan’s 2026 tax expansion also gives retirees a clear financial tailwind. All retirees can now subtract public and private retirement benefits up to an inflation-adjusted cap above 2025’s $131,794 joint limit, meaning a $65,000 couple owes zero state income tax on retirement income.
Plan ahead for winter utility bills and snow-clearing services. Setting aside extra cash each fall keeps freezing months stress-free.
2. Decatur, Illinois
Decatur earned the most affordable city spot in U.S. News rankings cited by AmeriSave in October 2026. Its overall cost of living sits at 90% of the national average, giving a $65,000 income extra breathing room.
A median home value around $89,855 makes cash purchases realistic for couples downsizing from pricier coastal suburbs. Avoiding a 7% mortgage saves tens of thousands of dollars over a decade.
Illinois exempts Social Security, pensions, and qualifying 401(k) or IRA distributions from state income tax. That puts Decatur among the most tax-efficient places to retire on 65000 a year.
Southern and Appalachian Gems Under the National Cost Average
If mild winters and low housing costs top your wish list, Southern towns stretch retirement dollars rapidly. Many also offer hospital hubs and friendly senior populations.
3. Fort Smith, Arkansas
Fort Smith delivers one of the lowest living thresholds in the country. BestPlaces data cited by FinanceBuzz estimates a minimum family living income here at just $29,520 a year—less than half your $65,000 budget.
Census 2020–2024 American Community Survey figures reported by RetireBetterNow put the median owner-occupied home value at $178,100 and median gross rent at $884 per month. FinanceBuzz’s November 2026 market snapshot tracks average homes at $195,029 and average rents at $989.
Two major medical centers—Baptist Health-Fort Smith and Mercy Hospital Fort Smith—serve residents locally. Arkansas also exempts Social Security from state income taxes.
4. Greeneville, Tennessee
Tucked near the Appalachian foothills, Greeneville appeals to couples who want mountain scenery without tourist-town markups. FinanceBuzz reports average home prices at $244,471 and average rents around $1,050 monthly as of November 2026.
Roughly 20% of Greeneville residents are age 65 or older, creating an established network of community groups and civic clubs. You will find plenty of peers who share similar schedules—U.S. Bureau of Labor Statistics data shows adults 65 and older average 7.11 hours daily on leisure and sports.
Tennessee imposes no personal income tax on wages, Social Security, or retirement account withdrawals. Every dollar of your $65,000 stays free from state income taxes.
5. Macon, Georgia
Macon combines historic architecture, music heritage, and rock-bottom housing prices in central Georgia. Average home prices sit around $171,522 with average rents near $1,150 per month, according to FinanceBuzz’s November 2026 data.
Serving as Bibb County’s regional healthcare hub, Macon keeps clinics and hospital care close to home. That proximity matters when routine specialist visits become part of your calendar.
Georgia exempts Social Security benefits and grants residents age 65 and older an exclusion of up to $65,000 per person on retirement income. A retired couple can shelter up to $130,000 annually from Georgia state income taxes.
6. Sebring and the Highlands Hammock Area, Florida
Coastal Florida often busts modest budgets, yet inland central Florida around Sebring and Highlands Hammock State Park remains remarkably affordable. Cheapism’s August 2026 report notes median home values near $175,000 and rents below $1,000 a month.
Florida remains the nation’s top retirement destination, offering more than 100 local lakes, two general hospitals, and zero state income tax. You get warm-weather fishing and state park boardwalks without beachfront prices.
Still, check homeowners insurance quotes before making an offer in Florida. Rising property insurance premiums can add thousands per year and reshape your total ownership costs.
Desert and Mountain West Towns for Active Couples
Western towns typically cost slightly more to buy into than the Midwest or Deep South, yet lower utility or tax burdens can balance the math. Look closely at HOA structures and state benefit rules before relocating west.
7. Green Valley, Arizona
Located 20 miles south of Tucson, Green Valley earned a spot on Forbes’ Best Places to Retire in 2026 with a median single-family home price of $282,000. That sits well below Zillow’s national typical home value of $364,288.
This unincorporated community contains 130 mostly age-restricted 55+ developments built around recreation centers, pools, and hobby workshops. If you want built-in neighbors and low-maintenance yards, Green Valley simplifies daily life.
Arizona exempts Social Security benefits from state income tax. Just factor HOA dues into your monthly housing worksheet so recreation fees never catch you off guard.
8. Pahrump, Nevada
Named to RetireBetterNow’s October 2026 Top 10 Best Places to Retire on a Budget, Pahrump offers wide-open desert living in Nye County near Las Vegas. Couples find single-story homes, manufactured housing, and quiet 55+ communities at attainable prices.
Nevada levies no state personal income tax on Social Security, pensions, or IRA withdrawals. Living about an hour outside Las Vegas gives you easy access to major airport travel and specialty hospitals without paying metro housing prices.
9. Anaconda, Montana
Mountain lovers looking for small-town grit and outdoor access often look to Anaconda. FinanceBuzz data from November 2026 puts average home prices at $302,593 and average rents at $1,350 a month.
Around 26% of Anaconda residents are over age 65, giving this former copper-smelting town a strong senior presence. Trails, fishing streams, and big-sky views sit right outside town.
Run the tax numbers carefully before committing to Montana. Unlike 42 states and Washington, D.C., Montana is one of just eight states that still tax some Social Security benefits in 2026.
Northeast Towns Where Scenic Living Meets Predictable Budgets
People often assume the Northeast locks out retirees on $65,000, yet inland towns break that rule. Tax exemptions and small-town pacing make parts of Pennsylvania and upstate New York surprisingly viable.
10. Altoona, Pennsylvania
Altoona has a population near 43,500 per ReloMaps 2026 figures and earned a place on RetireBetterNow’s October 2026 Top 10 Best Places to Retire on a Budget. Surrounded by the Allegheny Mountains, it pairs small-city healthcare and shopping with low housing costs.
Pennsylvania boasts one of the country’s friendliest tax codes for retirees. The state fully exempts Social Security, pensions, and qualifying 401(k) or IRA distributions once you reach age 59½ and separate from service.
Keeping state income taxes at zero helps your $65,000 cover winter heating and property maintenance comfortably. You can focus your budget on local dining, rail history, and weekend drives.
11. Saranac Lake, New York
Set in the Adirondacks, Saranac Lake suits couples who prioritize lakes, forests, and four-season outdoor life over rock-bottom housing. FinanceBuzz’s November 2026 figures report average home prices of $337,496 and average rents around $2,500 a month.
Roughly 18% of residents are over age 65, supporting a lively arts and community calendar year-round. New York exempts Social Security and up to $20,000 per person in qualifying retirement income at age 59½ and older.
Because Saranac Lake rents run high, it works best on $65,000 if you bring strong equity to buy a modest home outright. Watch Adirondack winter heating costs closely when building your annual budget.
Common Retirement Traps When Moving to a Small Town
Even affordable small towns for retirement can squeeze a $65,000 budget if overlooked costs pile up after moving day. Watch out for these costly mistakes before signing a lease or purchase contract.
Smart retirement relocation starts with calculating what you keep after taxes, insurance, and healthcare—not just comparing home sticker prices.
- Ignoring state tax differences: Only eight states—Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah, and Vermont—tax some Social Security benefits in 2026, while 13 states broadly exempt pension and retirement income.
- Overlooking federal benefit taxes: Up to 85% of your Social Security can still be federally taxed based on combined income, affecting slightly over half of beneficiaries in 2026.
- Underestimating property insurance and winter bills: Cheap homes in Florida can carry steep homeowners insurance, while northern towns like Midland or Saranac Lake add heavy heating expenses.
- Taking on a 7%+ mortgage unnecessarily: Buying with a 7.13% to 7.49% 30-year mortgage eats up monthly cash flow that home equity downsizing could protect.
- Forgetting 2027 Medicare Part D shifts: The Part D maximum standard deductible rises from $615 in 2026 to $700 in 2027, and the out-of-pocket cap increases from $2,100 to $2,400.
- Missing hospital and long-term care limits: Original Medicare Part A carries a $1,736 inpatient hospital deductible in 2026 and charges $217 per day for skilled nursing days 21 through 100—and general spending surveys exclude major long-term care bills.
If your budget ever feels tight after relocating, check whether you qualify for local property tax relief or utility help. Tools like the National Council on Aging’s BenefitsCheckUp screen for state and federal assistance programs.
You can also look up local transportation, meal delivery, and caregiver support in any new county through the federal Eldercare Locator before choosing a neighborhood.
When to Consult a Professional
Relocating across state lines affects your taxes, Medicare network, and estate documents all at once. Speaking with the right specialist before you move prevents expensive surprises later.
Consult a Medicare counselor through your new state’s SHIP program—or compare local options on the Medicare Plan Finder—before December 7 Open Enrollment. Moving counties often triggers a Special Enrollment Period and changes which Medicare Advantage or Part D drug plans cover your doctors.
Meet with a fee-only financial planner or CPA if you recently stopped working and face Medicare IRMAA surcharges. Couples with modified adjusted gross income above $218,000 two years prior can file Form SSA-44 within 60 days of a notice to appeal based on lower current-year income.
Finally, hire an elder law attorney in your new state to update wills, healthcare proxies, and powers of attorney. Property titling and probate rules vary sharply across state lines.
Frequently Asked Questions About Small-Town Retirement on $65,000
Can a retired couple really live well on $65,000 a year in 2026?
Yes, especially in towns where typical homes cost $90,000 to $282,000 and state taxes spare retirement income. With average couple Social Security benefits reaching $38,856 in 2026 and $40,260 in 2027, modest withdrawals cover everyday bills comfortably.
How much should we budget for Medicare on a $65,000 income?
Plan on $4,869.60 per year for two standard Part B premiums in 2026 ($202.90 each monthly) plus $283 deductibles per person. Add stand-alone Part D drug premiums averaging $35.09 monthly in 2026 and projected at $36 in 2027, plus Medigap or copays.
Do any of these affordable towns tax Social Security benefits?
Ten of the 11 highlighted towns sit in states that completely exempt Social Security in 2026. Only Anaconda, Montana is in one of the eight states that still tax a portion of Social Security benefits.
What happens if one spouse keeps working part-time after moving?
If you claim Social Security before full retirement age, the 2026 earnings limit is $24,480 ($25,560 in 2027), with $1 withheld for every $2 earned above it. Once you reach full retirement age, no earnings cap applies.
Taking Your Next Step Toward Small-Town Retirement
Pick two or three towns from this list and spend a week renting locally during their toughest weather season—July in Macon or January in Midland—while testing grocery bills and clinic drive times. Running a real trial budget turns guesswork into confidence.
Information in this article reflects current rules as of the publication date and may change. Always confirm benefit details directly with Social Security Administration, Medicare.gov, or relevant government agencies before making decisions.
Last updated: November 2026. Medicare and Social Security rules change annually—always verify current details at official government sources.