Don’t DIY These Decisions
Navigating the intersection of Social Security, tax deductions, and Medicare requires nuanced expertise. Trying to manage these moving pieces without qualified assistance can create expensive errors.
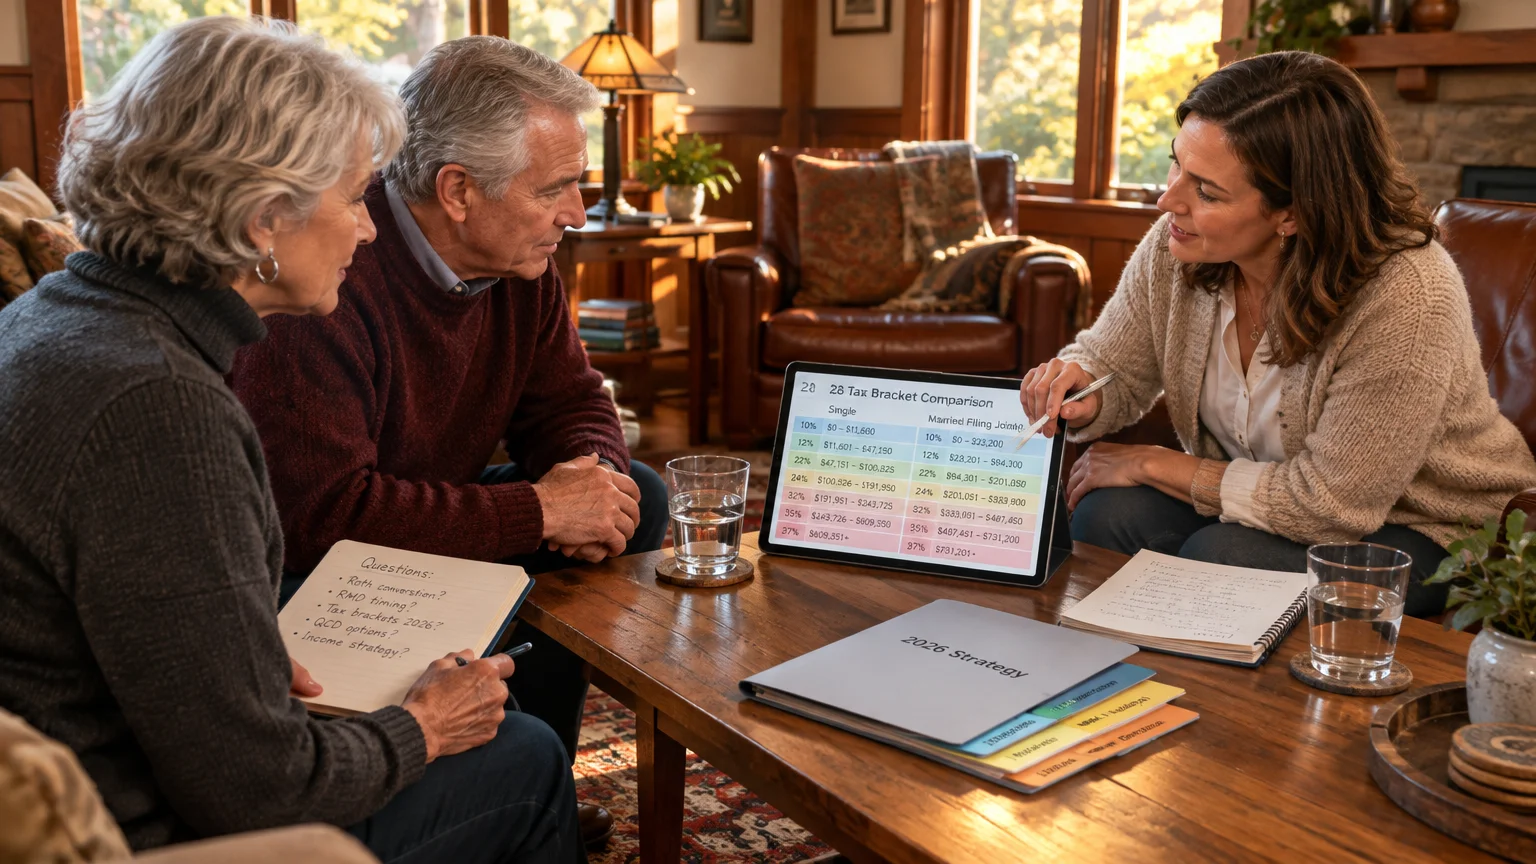
Work with a certified financial planner or tax professional who understands retirement decumulation. They can model your taxable income through 2028 to maximize the $6,000 deduction.
A tax advisor can also identify whether multi-year Roth conversions make sense before the 2028 sunset arrives. Strategic conversions can lock in lower tax rates while the Senior Bonus remains active.
If you are approaching retirement, consult a Social Security claiming specialist. They analyze spousal benefits, survivor protection, and breakeven ages to maximize lifetime cash flow.
When evaluating healthcare costs, reach out to your local State Health Insurance Assistance Program (SHIP). SHIP counselors provide free, unbiased guidance on Medicare enrollment and premium tiers.
For additional educational tools on retirement security, explore guidance provided by the Consumer Financial Protection Bureau. Professional guidance ensures you build a resilient, tax-optimized plan.