Costly Mistakes to Avoid During the Application Process
Beyond the grand strategies of when to claim, retirees frequently stumble over administrative hurdles that cost them dearly. Avoid these procedural errors as you approach your filing date:
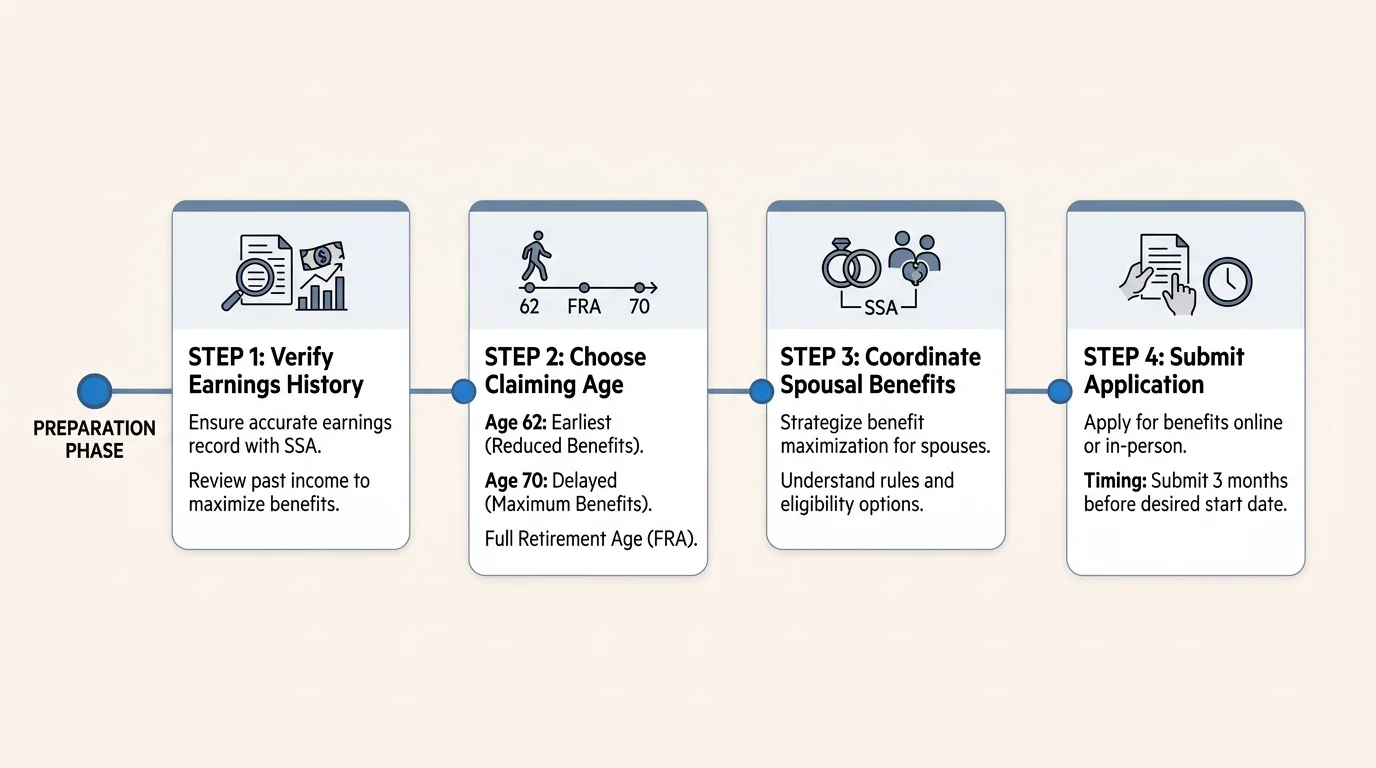
Failing to verify your earnings record. Your benefit amount relies entirely on your highest 35 years of indexed earnings. If the SSA has incorrect data—perhaps a former employer failed to report income, or a name change confused the system—your payout will shrink. Create a “my Social Security” account online and review your annual earnings statement. Correcting errors is much easier while you still have the W-2s and tax returns, rather than attempting to prove your income three decades later.
Failing to claim eligible ex-spouse benefits. If you were married for at least 10 years, have been divorced for at least two years, and are currently unmarried, you might be entitled to benefits based on your ex-spouse’s work record. Claiming this benefit has zero impact on your ex-spouse or their new partner. Many divorced retirees leave money on the table simply because they prefer not to reopen old wounds or remain unaware of the rule.
Messing up Medicare timing. While full retirement age for Social Security varies, Medicare eligibility begins strictly at age 65 for most Americans. If you delay Social Security past 65, you must still proactively enroll in Medicare. Missing your Initial Enrollment Period can trigger lifetime late enrollment penalties and leave you exposed to devastating medical bills.