6. Mandatory Roth Rules Take Full Effect for High-Earner Catch-Up Contributions
High-earning workers age 50 and older face strict retirement plan rules beginning January 1, 2027. Section 603 of the SECURE 2.0 Act now mandates after-tax Roth contributions for specific catch-up deposits.
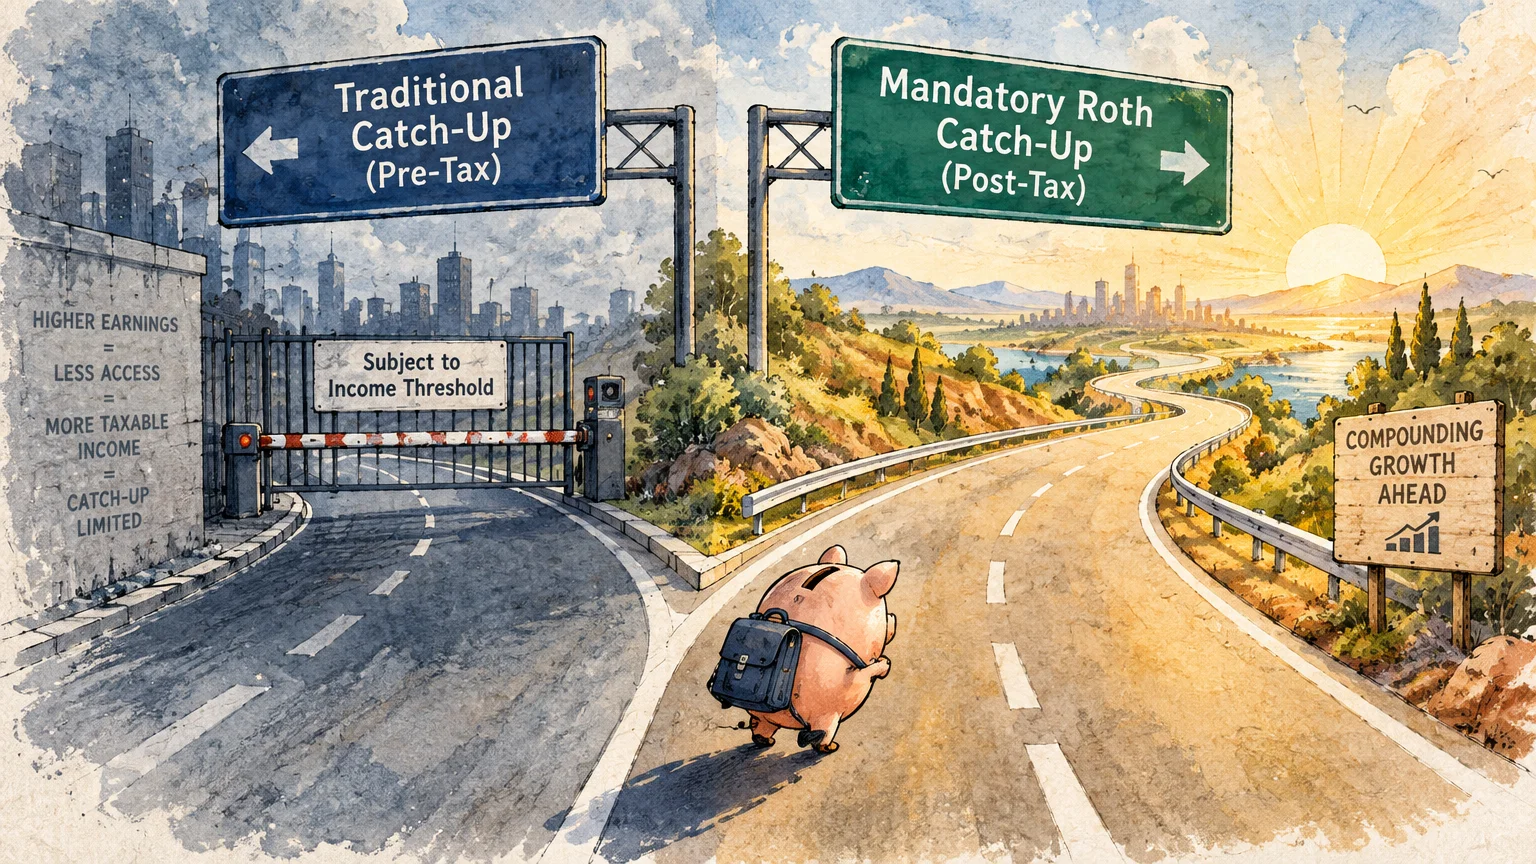
If you earned more than $145,000 in wages from your employer during the preceding year, you cannot make pre-tax catch-up contributions. All catch-up savings must flow directly into a designated Roth account.
The IRS allowed an extended transition period so plan administrators could update complex payroll platforms. That transition period ends in 2027 as final, mandatory compliance regulations take total legal effect.
You will lose the upfront tax deduction on those catch-up deposits, raising your taxable income for the current year. However, qualified withdrawals from your Roth balance will remain completely tax-free throughout retirement.
Check with your human resources department immediately to verify that your company retirement plan accommodates Roth savings. If your employer does not offer a Roth option, high earners cannot make catch-up contributions at all.