10. Increased Health Savings Account (HSA) Contribution Ceilings
Health Savings Accounts remain one of the most potent tools for building tax-free medical wealth. The IRS raised contribution ceilings under Revenue Procedure 2026-24 for the 2027 tax year.
Individuals with self-only qualifying high-deductible health coverage can save up to $4,500, up from $4,400. Family coverage limits climb to $9,000, providing a significant boost from the $8,750 cap in 2026.
Savers age 55 and older can contribute an additional $1,000 annual catch-up amount. This provision allows an older couple with family coverage to stash away a total of $11,000 tax-free.
Qualifying high-deductible health plans also adjust their baseline annual deductibles. Single coverage plans now require a minimum deductible of $1,750, while family plans require a minimum deductible of $3,500.
Remember that you must stop contributing to an HSA once you enroll in any part of Medicare. Contributing after Medicare coverage begins triggers steep tax penalties from the federal government.
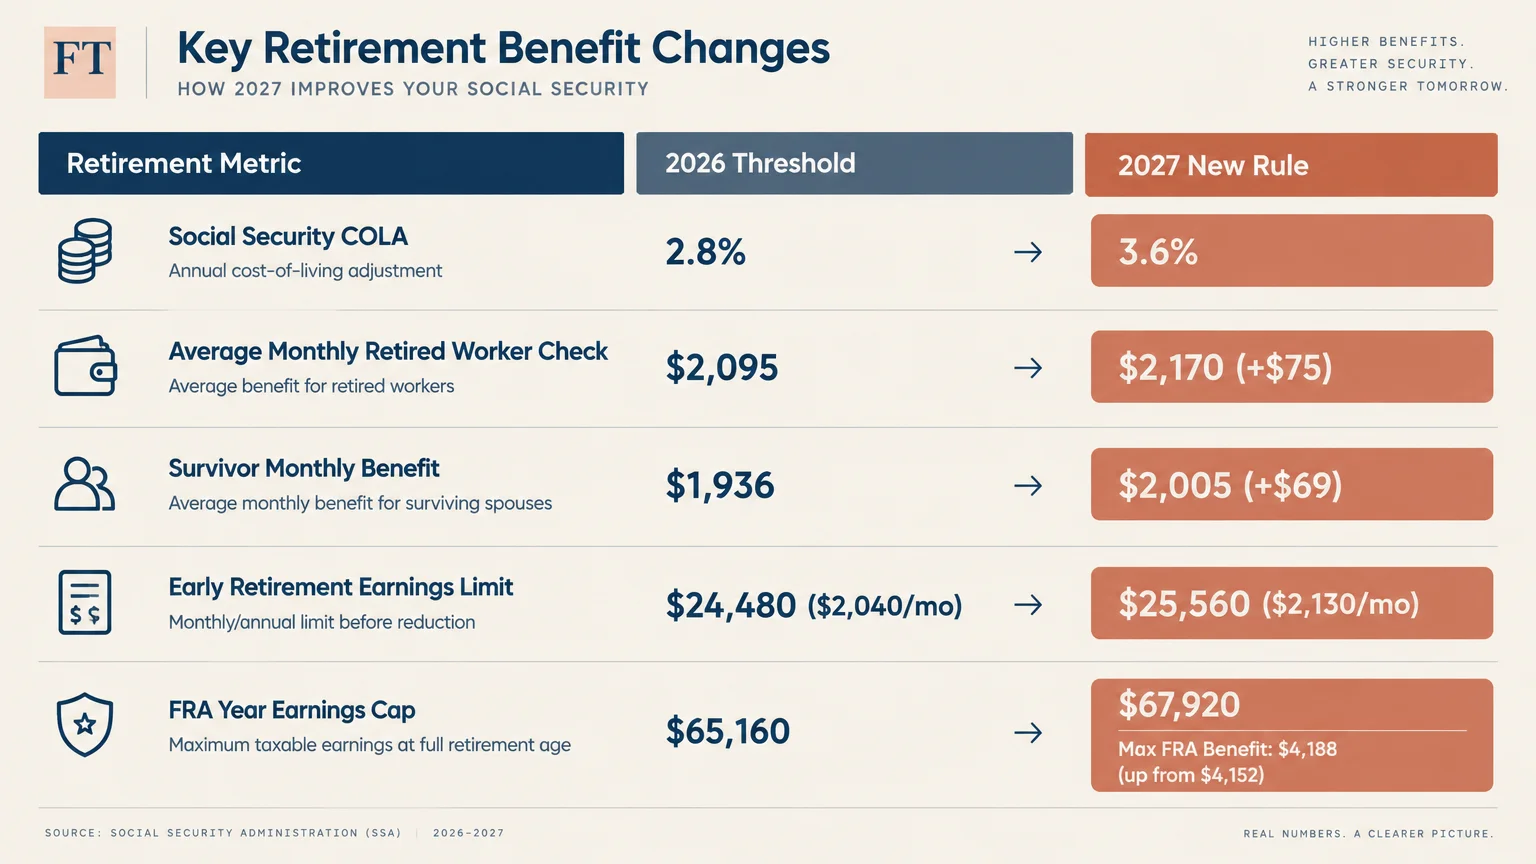
Key 2026 vs. 2027 Retirement Thresholds Compared
Comparing these updated regulatory thresholds side by side clarifies your strategic options for the year ahead. Small numerical changes across multiple programs often combine into significant annual shifts.
Use the summary table below to assess which retirement areas require immediate adjustments to your monthly cash flow.
| Retirement Provision | 2026 Rules | 2027 Rules | Strategic Action |
|---|---|---|---|
| Social Security COLA | 2.8% increase | 3.6% increase | Update personal cash flow projections. |
| Full Retirement Age (FRA) | 66 and 10 months (1959 births) | 67 years (1960 or later births) | Review claiming dates to prevent reductions. |
| Early Claiming Earnings Limit | $24,480 annually ($2,040/month) | $25,560 annually ($2,130/month) | Monitor part-time work to prevent benefit withholding. |
| FRA Year Earnings Limit | $65,160 annually ($5,430/month) | $67,920 annually ($5,660/month) | Coordinate final career bonuses before birthday month. |
| Max Social Security Benefit at FRA | $4,152 per month | $4,188 per month | Verify lifetime earnings records with SSA. |
| Payroll Tax Cap | $184,500 maximum earnings | $192,300 maximum earnings | Anticipate payroll deductions on late-career wages. |
| Social Security Work Credit | $1,890 per quarter credit | $1,970 per quarter credit | Earn at least $7,880 annually for full credits. |
| Standard 401(k) Deferral Limit | $24,500 | $25,500 | Increase workplace automated payroll deductions. |
| Age 50+ Catch-Up Limit | $8,000 | $8,500 | Target $34,000 total pre-retirement savings. |
| Ages 60–63 Super Catch-Up | $11,250 | $11,750 | Max out $37,250 workplace contributions. |
| Saver’s Incentive Program | Non-refundable Saver’s Credit | Federal Saver’s Match (up to $1,000) | Claim direct federal matching deposits in 2028. |
| High-Earner Catch-Up Rules | Transition period flexibility | Mandatory Roth contributions | Direct catch-up funds to designated Roth accounts. |
| Medicare Part D Out-of-Pocket Cap | $2,100 per year | $2,400 per year | Recalculate annual drug spending expectations. |
| Max Part D Deductible | $615 | $700 | Compare plan tiers during Medicare Open Enrollment. |
| HSA Limit (Self-Only) | $4,400 | $4,500 | Add $1,000 catch-up if age 55 or older. |
| HSA Limit (Family) | $8,750 | $9,000 | Fund medical savings before enrolling in Medicare. |
Evaluating these official metrics ensures you do not leave free money or valuable deductions on the table. Adjust your payroll elections and automated transfers early to hit these targets smoothly.
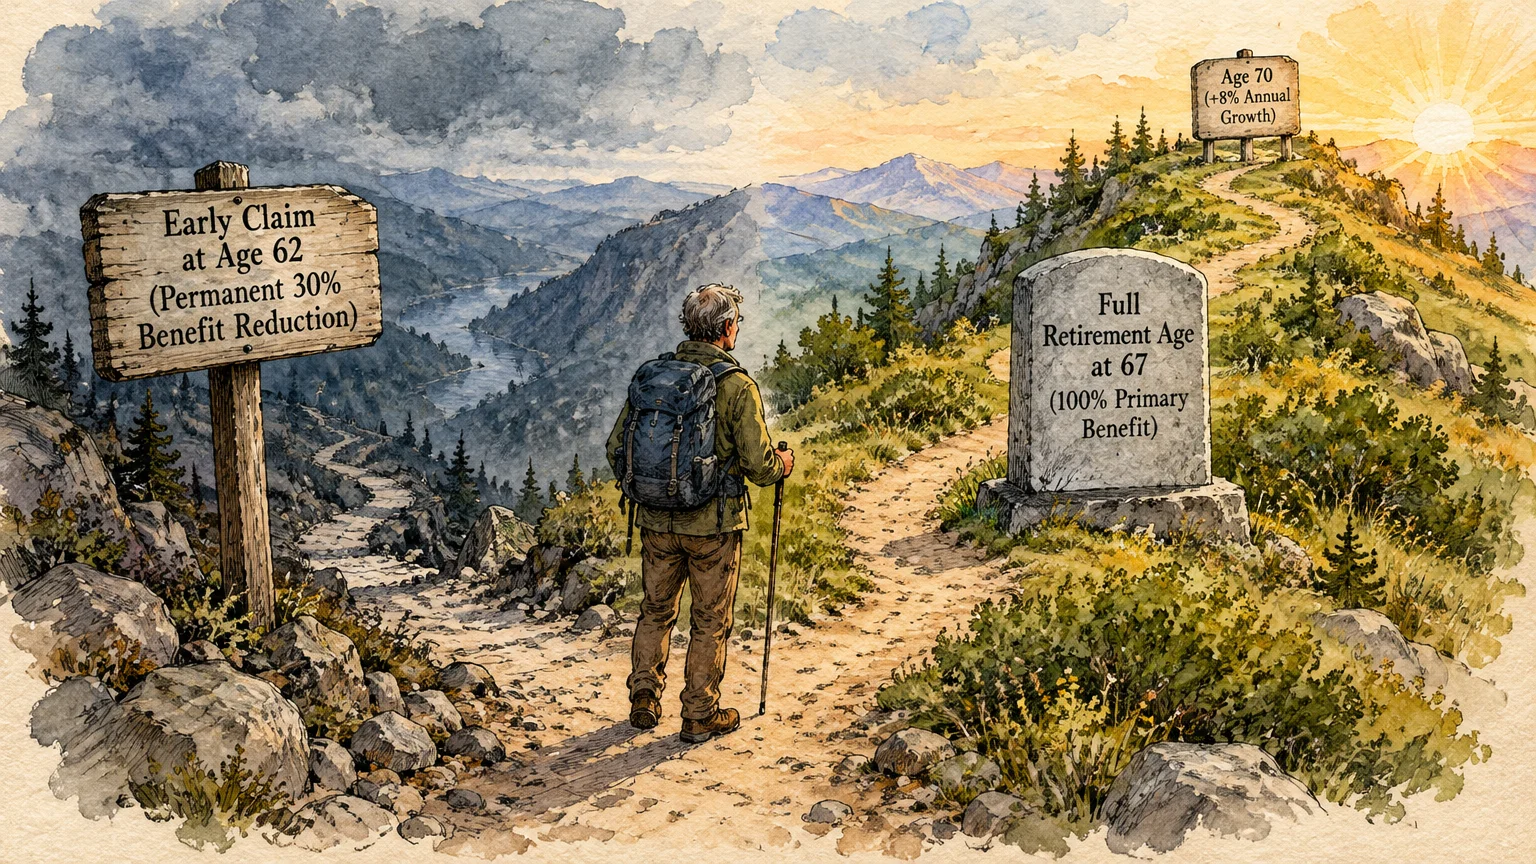
Costly Mistakes to Avoid
Changing regulations create frequent stumbling blocks for retirees who rely on outdated information. Avoiding these common missteps protects your wealth from unnecessary taxes and benefit forfeitures.
1. Triggering Social Security earnings penalties: Continuing to work while collecting early benefits before age 67 can temporarily reduce your monthly checks. Track your gross wages carefully so you do not exceed the $25,560 threshold.
2. Overlooking the Roth catch-up mandate: If your 2026 wages exceeded $145,000, failing to route your 2027 catch-up savings into a designated Roth account violates IRS regulations. Your plan administrator may reject non-compliant contributions outright.
3. Depositing into an HSA after enrolling in Medicare: Signing up for Medicare Part A or Part B ends your HSA contribution eligibility immediately. Continuing contributions generates a 6% excise penalty on excess funds for every year they remain.
4. Ignoring annual Medicare drug formularies: Even with the out-of-pocket cap rising to $2,400, individual plan formularies change every single year. Failing to review your medications during open enrollment could leave your vital prescriptions uncovered.
5. Missing the direct Saver’s Match deposit: Qualified low-to-middle earners frequently forget to designate an eligible retirement account for their match. Ensure your IRA or workplace account stands ready to receive the federal deposit in 2028.
Don’t DIY These Decisions
Complex tax legislation and healthcare reorganizations make professional guidance more valuable than ever. Handling intricate retirement choices without qualified counsel can create expensive, permanent consequences.
Social Security Claiming Strategy: Deciding between claiming at 62, 67, or 70 affects your lifetime cumulative wealth and survivor benefits. Work with a claiming specialist to analyze spousal strategies, health factors, and break-even ages.
Medicare Plan Selection: Navigating the differences between Original Medicare, Medigap, and Medicare Advantage requires objective evaluation. Connect with a local State Health Insurance Assistance Program (SHIP) counselor for free, unbiased guidance on regional plans.
Tax Diversification and Roth Conversions: Transitioning between pre-tax accounts, Roth balances, and taxable investments requires sophisticated tax modeling. A Fee-Only Certified Financial Planner (CFP) helps you navigate tax brackets while dodging Medicare premium surcharges.
Long-Term Care and Estate Protection: Healthcare emergencies can rapidly consume decades of retirement savings without proper legal barriers. Consult an elder law attorney to establish medical directives, living trusts, and Medicaid asset protection structures.
Frequently Asked Questions About 2027 Retirement Rules
Does the 3.6% Social Security COLA trigger higher taxes on my benefits?
It might. Federal tax thresholds for Social Security benefits ($25,000 for single filers and $32,000 for couples) are not indexed to inflation, meaning higher benefits can push you into taxable territory.
What happens if I earn more than the 2027 retirement earnings limit?
The SSA withholds $1 of benefits for every $2 earned above $25,560 if you are below FRA all year. Once you reach 67, the agency recalculates your benefit to credit back withheld amounts over time.
Can I receive the SECURE 2.0 Saver’s Match as a cash tax refund?
No, the Saver’s Match is not a cash tax refund. The federal government deposits the matching funds directly into your qualified retirement account or IRA to build compounding wealth.
Who qualifies for the $50 copay under the Medicare GLP-1 Bridge program?
Qualifying Part D enrollees with established clinical diagnoses for covered health conditions can access eligible GLP-1 medications. You must verify that your prescribing physician and plan participate in the initiative.
Taking Action on Your 2027 Retirement Plan
Preparing for these ten regulatory adjustments gives you a distinct advantage as 2027 unfolds. Review your payroll deductions, verify your Social Security claiming plans, and compare your healthcare options early.
- Audit your payroll withholdings: Adjust your 401(k) and HSA contributions to capture the higher 2027 annual limits.
- Confirm your Roth contribution setup: Ensure your workplace retirement plan supports Roth catch-up deposits if your prior-year earnings exceeded $145,000.
- Review your Part D drug formulary: Verify that your medications remain covered under the $2,400 out-of-pocket prescription cap.
- Check your Social Security earnings: Keep your earned income below $25,560 if you work while collecting benefits before Full Retirement Age.
Proactive planning today guarantees that federal policy shifts work in your favor rather than against your budget. Take deliberate steps now to maximize your savings and preserve your financial independence throughout retirement.
This article is for informational purposes only and does not constitute financial, legal, or medical advice. Medicare rules, Social Security benefits, and tax laws change regularly—verify current details at Medicare.gov, SSA.gov, or with a licensed professional.
Last updated: February 2026. Medicare and Social Security rules change annually—always verify current details at official government sources.