Who Benefits Most From High-Deductible Coverage?
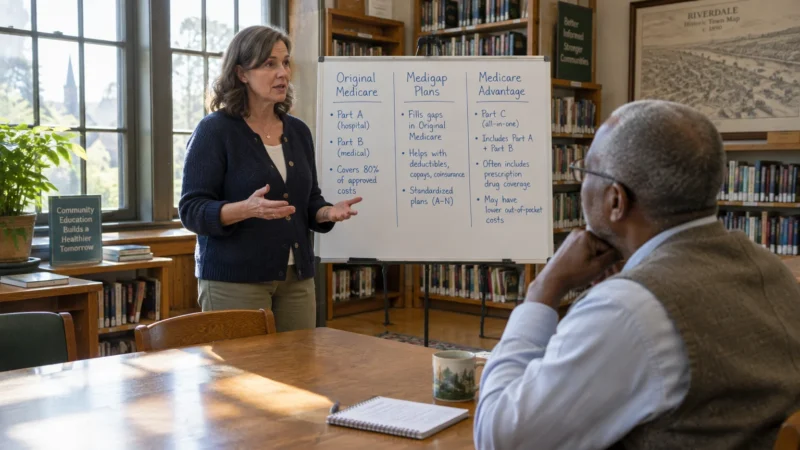
High-deductible Medicare Supplement plans are not designed for every retiree. However, they provide outstanding mathematical value for specific groups of older adults.
Healthy retirees transitioning from employer coverage. If you rarely visit doctors beyond routine preventive checkups, paying high monthly premiums for standard Plan G wastes money. Preventive visits remain covered by Medicare at zero cost to you.
Retirees with dedicated emergency funds. If you possess $3,050 in liquid cash to cover a sudden health event, taking the high-deductible route makes financial sense. You retain control of your capital rather than handing it to an insurance carrier.
Travelers who want nationwide doctor access. Medicare Advantage plans often restrict care to regional HMO or PPO networks. High-deductible Medigap gives you nationwide freedom to see any physician accepting Medicare at a fraction of standard Medigap premiums.
Educational groups like AARP frequently note that evaluating your personal risk tolerance is essential when picking supplemental insurance. If receiving medical bills causes anxiety, standard coverage may offer greater peace of mind.
Strategic Financial Moves to Prepare for 2027
Preparing for the $3,050 deductible requires simple, proactive adjustments to your cash management strategy. Take these practical steps before January 1 arrives.
First, establish a dedicated healthcare reserve account. Deposit the monthly premium savings generated by your high-deductible policy directly into a high-yield savings vehicle.
Over two years, your premium savings alone can fully fund the entire $3,050 deductible. Once that reserve exists, you effectively self-insure against unexpected healthcare expenses.
Second, review your Social Security benefit status and income withholdings. Coordinating your healthcare budgeting with retirement cash flow ensures predictable monthly finances through the Social Security Administration.
Third, ensure you pair your supplement with a competitive standalone Medicare Part D drug plan. Because prescription drugs do not count toward your Medigap deductible, selecting an affordable drug formulary protects your routine cash flow.
Finally, keep an organized folder for your Explanation of Benefits statements. Tracking your out-of-pocket payments ensures your Medigap insurer steps in immediately once you reach the $3,050 threshold.