Errors That Cost Retirees Thousands
Choosing high-deductible coverage without understanding the fine print leads to expensive errors. Avoid these five common pitfalls to protect your retirement balance sheet.
Assuming you pay $3,050 before Medicare pays anything. Many beneficiaries mistakenly believe high-deductible Medigap delays all healthcare payments. Remember that Original Medicare pays its 80% share immediately for outpatient services.
Expecting prescription drugs to count toward the deductible. Medigap plans do not cover outpatient retail prescriptions. Money spent on Part D medications never counts toward your $3,050 Medigap threshold.
Spending your premium savings on discretionary items. Enrolling in a high-deductible plan saves money on monthly premiums. If you spend those savings instead of banking them in a reserve fund, a sudden illness creates financial stress.
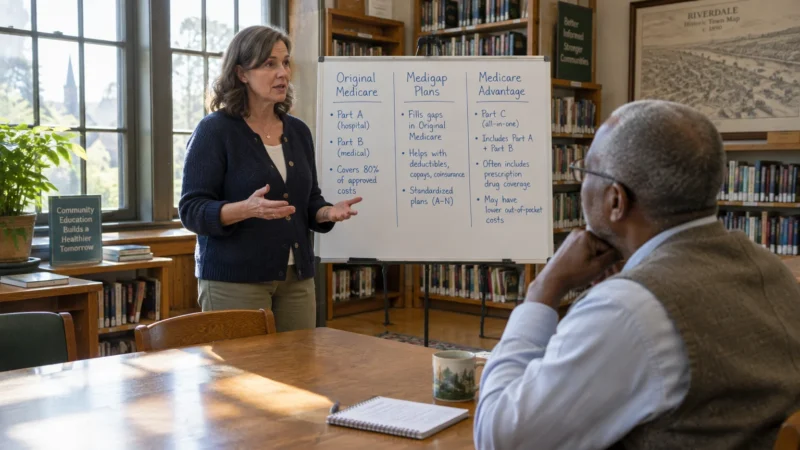
Confusing Medigap with Medicare Advantage. Some retirees confuse this deductible with a Medicare Advantage maximum out-of-pocket limit. Medigap maintains nationwide provider access with zero network restrictions or prior authorization roadblocks.
Failing to track Medicare Summary Notices. Medical billing offices occasionally miscalculate patient responsibility amounts. Review your statements quarterly to ensure billing departments credit your payments correctly toward your annual cap.
A Step-by-Step Scenario: Hitting the Deductible
Walking through a realistic medical scenario clarifies how the $3,050 deductible functions during a calendar year. Consider an individual enrolled in High-Deductible Plan G who faces hospital care.
In February, you visit a specialist and undergo diagnostic outpatient imaging. The Medicare Part B approved amount totals $1,200.
You pay the Part B baseline deductible first. Assuming the baseline cost matches the 2026 figure of $283, you pay that amount directly to the clinic.
Medicare pays 80% of the remaining $917 balance, leaving you with a 20% coinsurance payment of $183.40. Your total out-of-pocket spending for February stands at $466.40, which credits directly toward your $3,050 deductible.
In June, you require an unexpected three-day inpatient hospital stay. The Medicare Part A deductible applies, which equaled $1,736 in 2026.
You pay the $1,736 hospital deductible out-of-pocket. Adding this to your previous $466.40 brings your year-to-date spending to $2,202.40.
In September, you undergo physical therapy sessions with cumulative coinsurance charges totaling $900. You pay $847.60 of those bills, which brings your cumulative spending to exactly $3,050.
At that precise moment, you satisfy your High-Deductible Plan G requirement. For the remainder of that calendar year, your Medigap policy pays 100% of all Medicare-approved coinsurance and copayments.