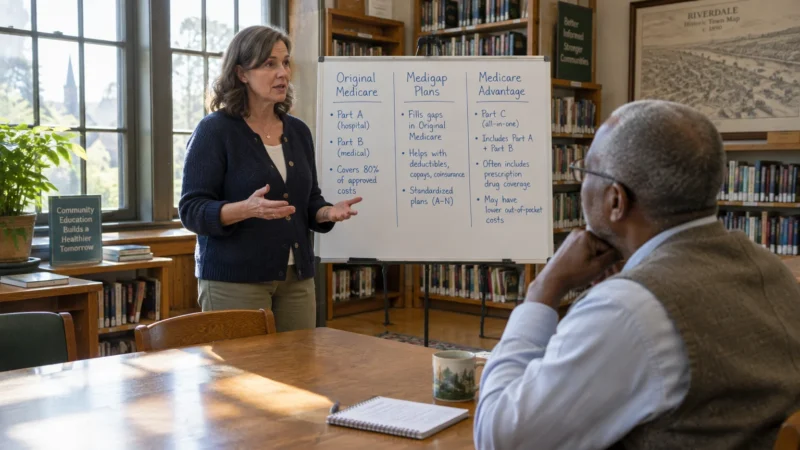
When to Get Expert Help
Navigating supplemental Medicare rules can feel overwhelming when health needs change. Consulting qualified professionals ensures you make decisions aligned with your long-term interests.
Contact your local State Health Insurance Assistance Program for free, objective guidance. SHIP counselors provide unbiased advice without sales pressure or commercial commissions.
Work with an independent, licensed Medicare insurance broker if you wish to compare specific carrier rates. Independent agents represent multiple insurers and can explain underwriting rules in your state.
Consult a fee-only fiduciary financial advisor when integrating healthcare costs into comprehensive estate or retirement income plans. Fiduciaries help balance out-of-pocket medical risks against investment portfolios.
Engage an elder law attorney if you anticipate long-term care needs or Medicaid planning. Standard Medicare and Medigap policies do not cover custodial nursing home care, making specialized legal planning essential.
Frequently Asked Questions About the Medicare $3,050 Deductible
Does the $3,050 deductible reset every calendar year?
Yes. The high-deductible Medigap threshold resets on January 1 of each calendar year, regardless of when you enrolled in the policy.
Do my monthly Medigap premiums count toward the $3,050 deductible?
No. Monthly insurance premiums never count toward the deductible. Only Medicare-approved out-of-pocket deductibles, copayments, and coinsurance apply toward the limit.
Can I switch from High-Deductible Plan G to standard Plan G later?
In most states, switching policies after your initial Medigap open enrollment window requires medical underwriting. Insurers can review your medical history and may deny coverage or charge higher rates.
Does Original Medicare still pay if I have not met the $3,050 deductible?
Yes. Original Medicare pays its standard share of covered Part A and Part B claims from day one. You only pay your normal coinsurance and deductible shares until hitting the cap.
Taking Action on Your Healthcare Plan
The increase to a $3,050 deductible in 2027 should not cause alarm if you hold high-deductible Medigap coverage. It simply reflects regular inflation indexing mandated by federal law.
Take time today to verify your policy documents, review your liquid medical savings, and calculate your annual premium savings. A small amount of preparation keeps your retirement healthcare secure, affordable, and fully under your control.
This article is for informational purposes only and does not constitute financial, legal, or medical advice. Medicare rules, Social Security benefits, and tax laws change regularly—verify current details at Medicare.gov, SSA.gov, or with a licensed professional.
Last updated: November 2026. Medicare and Social Security rules change annually—always verify current details at official government sources.