Retirees in USA

Live, Laugh, Retire: Real Insights for American Seniors

  • HEALTHY AGING
  • NEWFOUND FREE TIME
  • RETIREES’ TOP CHOICES
  • RETIREMENT INCOME

What Medicare Does NOT Cover — And How Retirees Are Paying for the Gaps

March 7, 2026 · By Retirees in USA Editorial Team · RETIREMENT INCOME
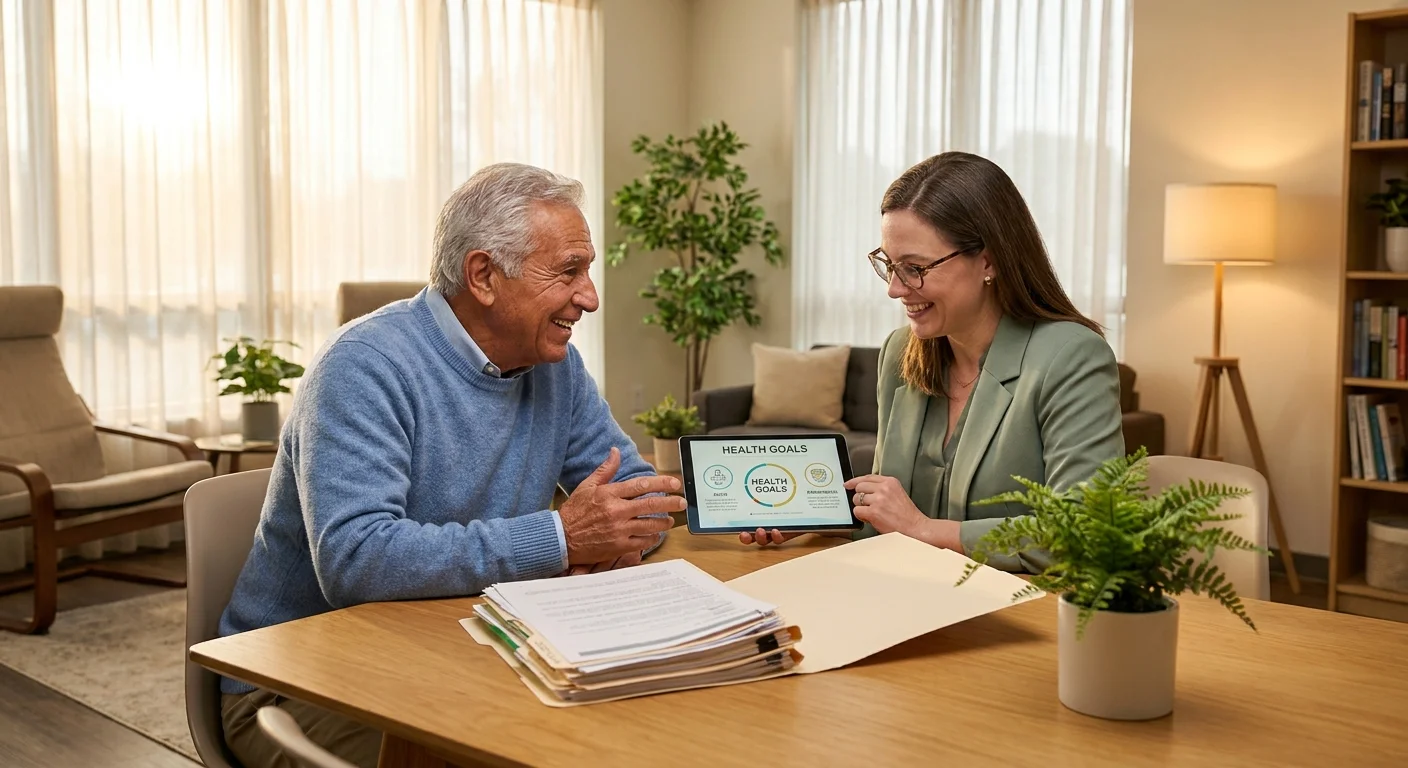
A senior man consults with a professional about Medicare gap coverage in a bright community center.
A professional advisor helps a retiree explore his best options for filling coverage gaps using a tablet.

Part Five: Your Four Best Options for Filling the Gaps

The good news is that the gaps in Medicare are well known, and an entire ecosystem of insurance products and programs has been built specifically to address them. Here are the four primary strategies retirees use, and what each one is best suited for.

Option 1: Medicare Supplement Insurance (Medigap)

Medigap plans are sold by private insurance companies and are designed to work alongside Original Medicare—paying for costs that Medicare leaves behind, such as deductibles, coinsurance, and copayments.

In most states, Medigap plans are standardized and labeled with letters: Plan G and Plan N are currently the most popular choices for new enrollees.

What Medigap Typically Covers: Medicare Part A coinsurance and hospital costs (up to an additional 365 days). Medicare Part B coinsurance or copayment (usually 80% of the remaining 20%). Part A deductible (depending on plan). Foreign travel emergency care (Plans C, D, F, G, M, N — up to plan limits).  Skilled nursing facility coinsurance. Note: Medigap does NOT cover dental, vision, hearing, or long-term care

The best time to enroll in Medigap is during your six-month Medigap Open Enrollment Period, which begins the month you turn 65 and are enrolled in Part B. During this window, insurers cannot deny you coverage or charge you more based on your health history. Outside this window, medical underwriting applies in most states.

Monthly premiums for Medigap plans vary widely by plan type, insurer, age, and location — generally ranging from $100 to $400+ per month. For retirees who want maximum financial predictability and see many doctors, Medigap is often the most cost-effective long-term solution.

Option 2: Medicare Advantage (Part C)

Medicare Advantage plans are an alternative to Original Medicare — rather than supplementing it, they replace Parts A and B entirely and are administered through private insurers approved by Medicare. Most Medicare Advantage plans also include Part D drug coverage and frequently bundle in dental, vision, and hearing benefits that Original Medicare does not cover.

Medicare Advantage plans often have lower monthly premiums than Medigap — some plans have $0 premiums — but they typically use provider networks (HMO or PPO structures), meaning your choice of doctors and hospitals may be restricted. They also commonly require prior authorization for certain procedures and may have higher out-of-pocket costs if you need significant care.

Medicare Advantage works best for retirees who are relatively healthy, prefer a structured plan with bundled benefits, and are comfortable staying within a network of providers. It may be less suitable for retirees with complex medical needs who want unrestricted access to specialists.

Option 3: Medicare Part D (Prescription Drug Coverage)

Original Medicare does not cover most prescription drugs you take at home — that gap is addressed by Part D plans, which are purchased separately through private insurers or included in a Medicare Advantage plan. In 2026, significant changes have continued rolling in from the Inflation Reduction Act, including a $2,000 annual out-of-pocket cap on Part D drug costs — a major improvement for retirees who take expensive medications.

If you do not enroll in Part D when you are first eligible and do not have other creditable drug coverage, you may face a late enrollment penalty for as long as you have Medicare. Even if you currently take few medications, enrolling in a low-premium Part D plan at 65 is generally advisable.

Option 4: Long-Term Care Insurance

Because Medicare provides virtually no coverage for custodial long-term care, long-term care insurance remains an important planning tool for many retirees. A traditional long-term care policy pays a daily or monthly benefit when you need help with activities of daily living — typically two or more of bathing, dressing, eating, continence, toileting, or transferring.

The challenge: traditional long-term care insurance premiums have increased substantially over the years, and many insurers have exited the market. Hybrid products — such as life insurance policies with a long-term care rider — have become a popular alternative because they guarantee a death benefit even if long-term care is never needed.

Financial planners generally recommend evaluating long-term care coverage options in your mid-50s to early 60s, when premiums are lower and health qualifications are easier to meet. Waiting until your late 60s or 70s can significantly increase costs or make coverage unavailable.

Pages: 1 2 3 4 5 6 7

Share this article

Facebook Twitter Pinterest LinkedIn Email
Written by

Retirees in USA Editorial Team

The Retirees in USA Editorial Team is dedicated to helping American seniors and pre-retirees navigate every stage of retirement with confidence and clarity. Our content is thoroughly researched using authoritative sources — including SSA.gov, Medicare.gov, AARP, the National Council on Aging, IRS.gov, and CDC.gov — and reviewed for accuracy, practical value, and relevance before publication. We cover healthy aging, retirement income, Medicare, Social Security, senior lifestyle, and everything in between. Our mission is simple: give real people real answers about the retirement questions that matter most. All content on Retirees in USA is editorially reviewed and verified before going live.
See our Editorial Policy for full details on how we work.

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • A woman walking along a path by a coastal marsh and houses at dawn with a shrimp boat on the water. 10 Island and Coastal Towns Worth Considering for Retirement
  • Senior man standing by a brick mailbox outdoors, reviewing a plain white envelope among a stack of colorful flyers. 7 Medicare Letters That Look Like Junk Mail but Aren't
  • An older woman and man smiling while shaping clay bowls on pottery wheels in a sunlit art studio. 10 Ways to Stay Social When You Live Alone
  • A smiling mature couple rides bicycles with grocery-filled baskets along a paved riverside path near a city skyline. 12 Cities Retirees Say Beat Expectations on Cost and Comfort
  • Three smiling older adults garden together in raised beds and hold harvested carrots outside a town hall. 12 Places Retirees Say Feel Like a Real Community
  • Older man in an apron watering potted tomato plants and red flowers on a sunny apartment balcony overlooking a street. 10 Retirement Spots Where Rent Is Still Under $1,200
  • A car drives along a road above underground tanks labeled with various fees that siphon gold coins. 8 Costs Retirees Forget When Comparing Two States
  • A smiling woman selects apples at an outdoor autumn market on a wet brick street before a historic clock tower building. 12 Retirement-Friendly Cities Beyond the Sunbelt
  • A woman checks her long grocery receipt at a checkout counter filled with produce and bags. 8 Things the Next COLA Announcement Could Change for Your Budget
  • Older couple wearing Santa hats waves from a golf cart decorated with Christmas lights during an evening holiday parade. 10 Retirement Communities Known for Great Holiday Traditions

Newsletter

Get retirement tips, Medicare guides, and senior living advice delivered to your inbox.

Related Articles

7 Ways to Spend Your Retirement Nest Egg Wisely

First, congratulations on your amazing achievement. After working hard and saving, it’s showtime! How can…

Read More →
Older man in glasses sitting at a kitchen table writing in a notepad beside mail, a calculator, and steaming coffee.

9 Retirement Expenses That Add Up to $2,000 a Month

See how nine essential living costs add up to $2,000 a month in retirement and…

Read More →
A senior man sitting at a kitchen counter, focused on reviewing an official Medicare overpayment notice under soft morning light.

Medicare Overpayment Notices: What to Do If You Get One

Received a Medicare overpayment notice? Learn how to halt benefit withholding, file appeals, request fast-track…

Read More →
Close-up of a senior's hands organizing neat folders and medical files on a sunlit wooden table alongside a mug of coffee.

10 Documents That Speed Up a Disability Application

Gather these 10 essential documents for your Social Security disability application to prevent administrative delays…

Read More →

Optimizing Your Retirement Finances: Lessons from Behavioral Economics

Picture this: You’re driving a vintage convertible with the wind in your hair toward a…

Read More →
An elegant gouache illustration of a professional woman in her 50s confidently stepping up a series of rising colorful blocks.

50 Highest-Paying Jobs in America Right Now, According to Data

Discover the 50 highest-paying jobs in America right now and learn how maximizing your late-career…

Read More →

What Is the Best Age to Claim Social Security? The Real Answer for Your Situation

A bookmarked Social Security Handbook and tax forms sit on a desk, highlighting the hidden…

Read More →
A retired couple smiling as they pay for fresh vegetables with a cash back credit card at a sunny outdoor farmers' market.

The Best Credit Cards for Retirees Who Love Cash Back

Discover how retirees can maximize their fixed income and effortlessly offset everyday expenses by strategically…

Read More →
An older couple sitting at a wooden dining table, reviewing financial planning documents together in warm morning light.

8 Retirement Income Gaps Retirees Often Discover Too Late

Learn the 8 overlooked retirement income gaps—including taxes, Medicare limits, and RMD cliffs—and discover practical…

Read More →
Retirees in USA

Live, Laugh, Retire: Real Insights for American Seniors

Inedit Agency S.R.L.
Bucharest, Romania

contact@retireesinusa.com

Trust & Legal

Home

About Us

Advertiser Disclosure

Disclaimer

Editorial Policy

Contact

Privacy Policy

Terms and Conditions

Subscribe

Unsubscribe

Categories

  • HEALTHY AGING
  • NEWFOUND FREE TIME
  • RETIREES' TOP CHOICES
  • RETIREMENT INCOME
  • Uncategorized

© 2026 Retirees in USA. All rights reserved.